

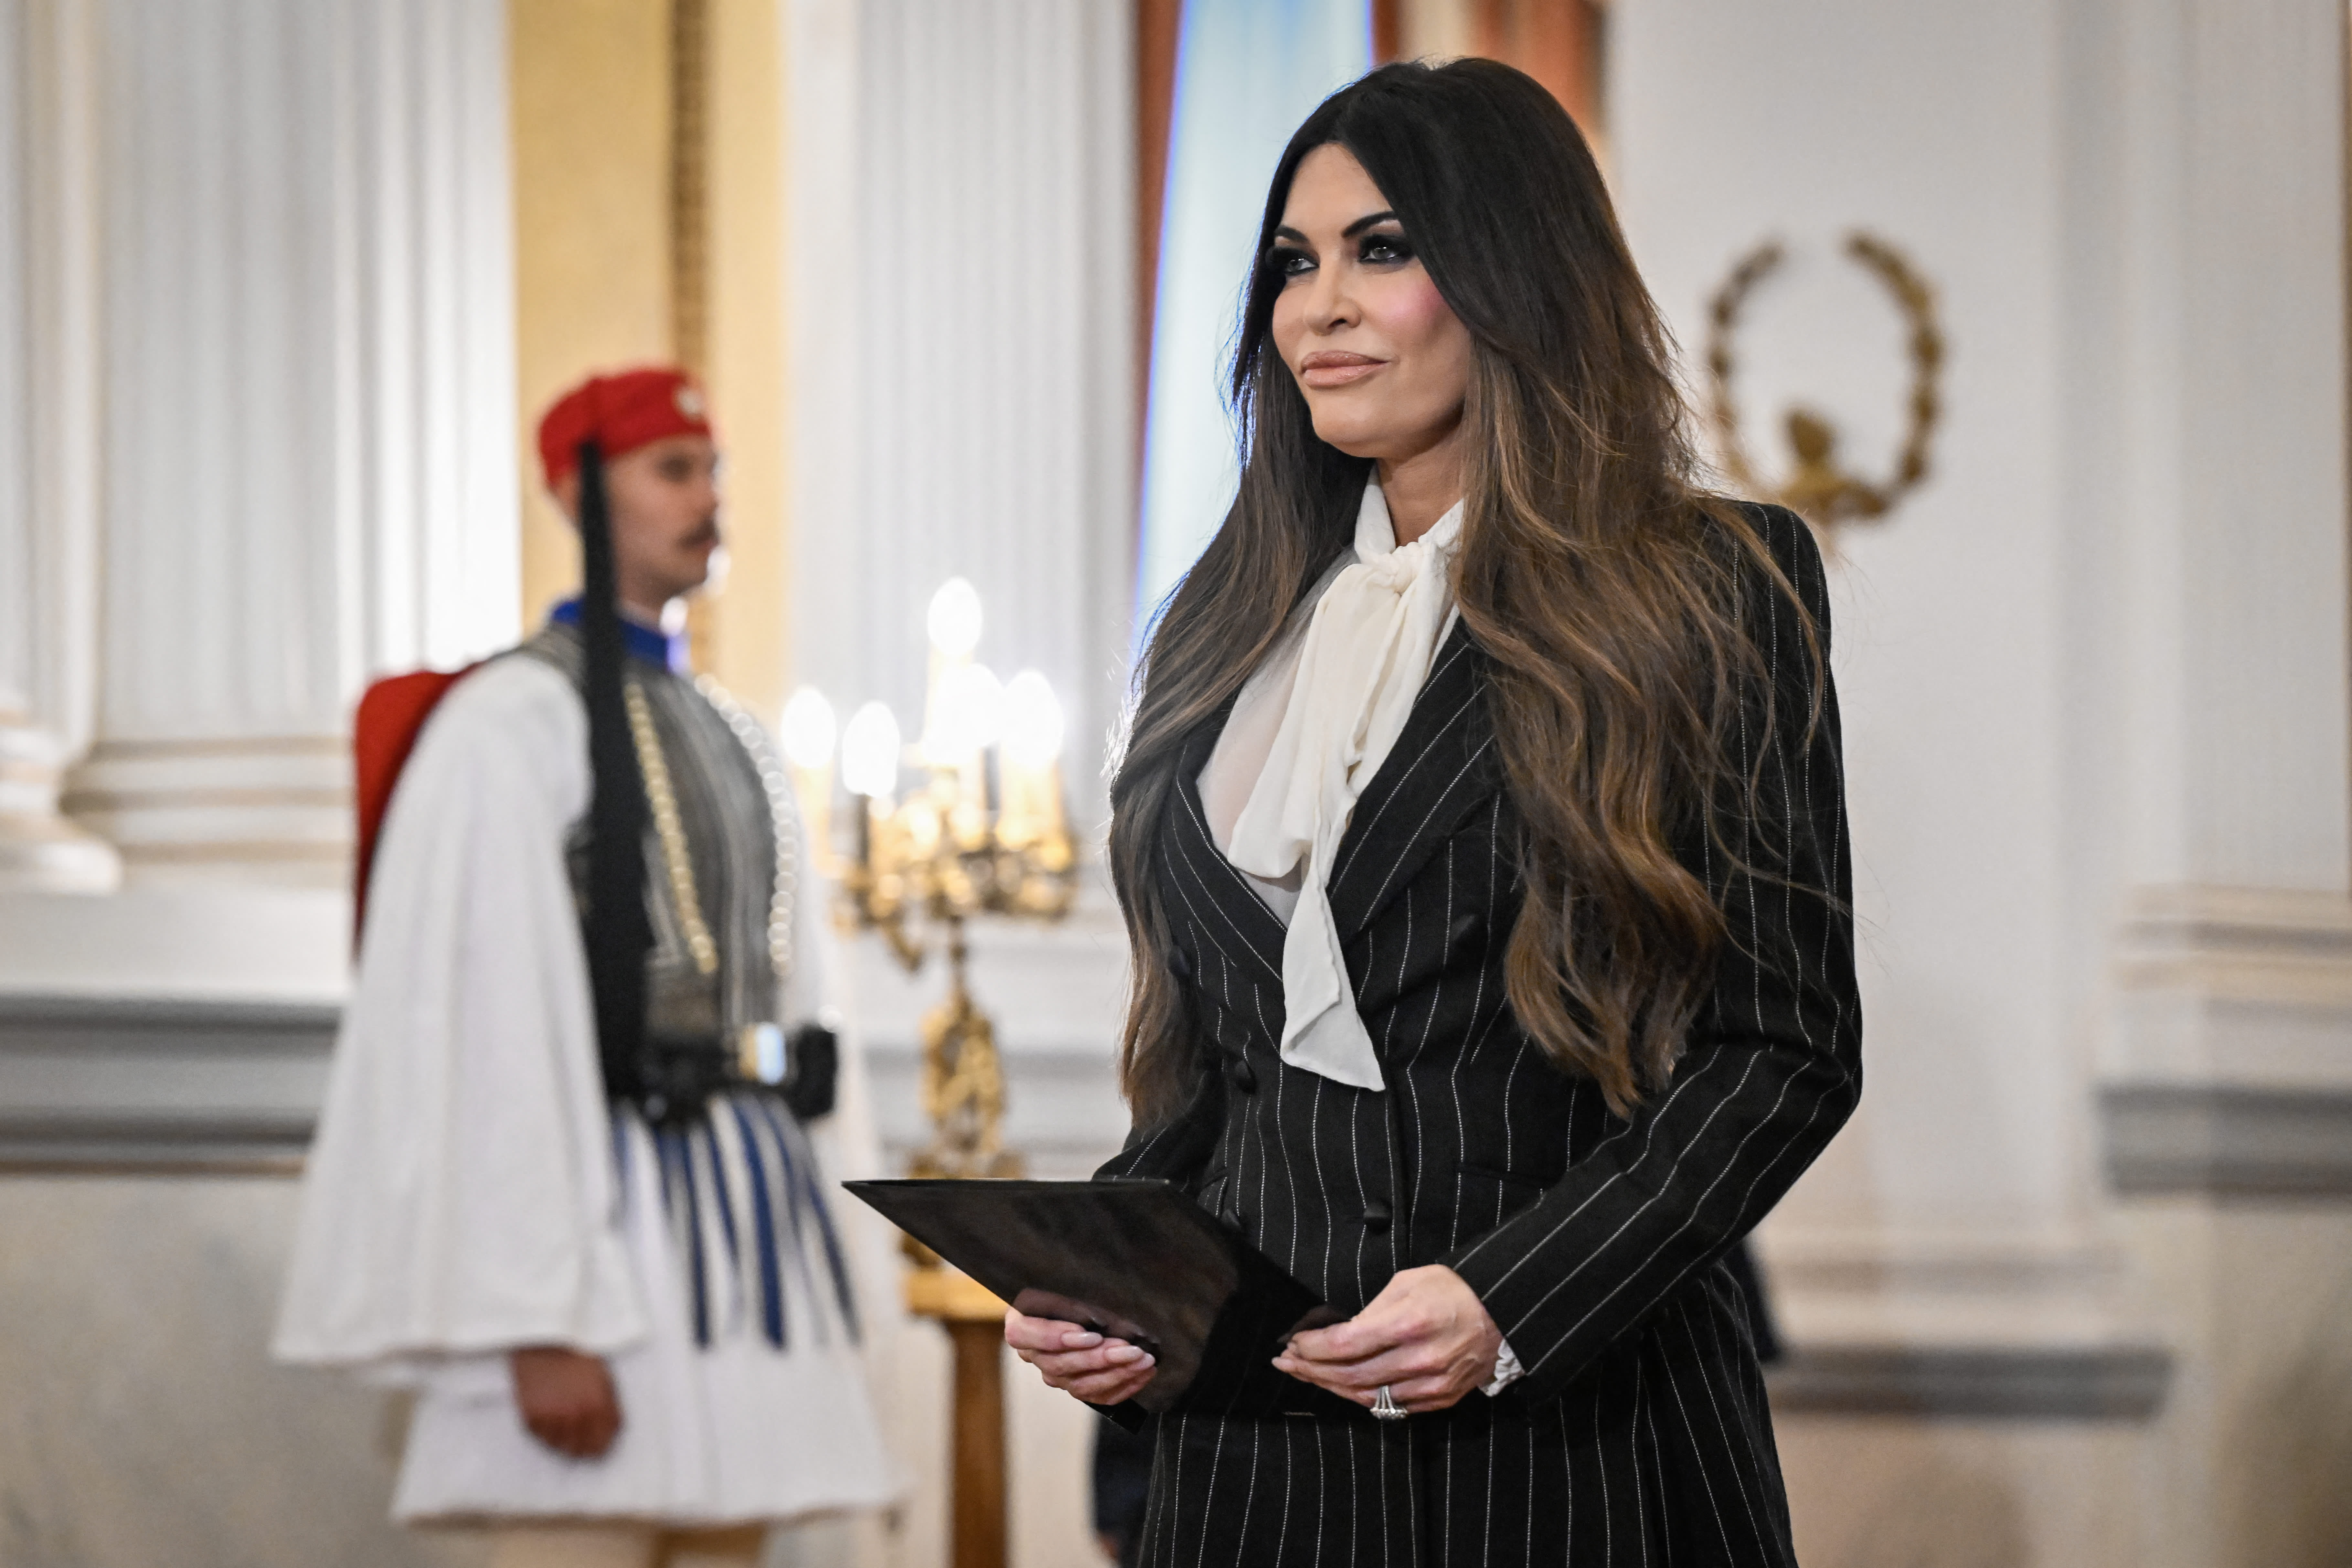
The abrupt resignation of US Ambassador Kimberly Guilfoyle — forced by the White House following allegations of improper conduct during her tenure — created an immediate political ripple in Athens. The government treated the matter with deliberate detachment, with its spokesman describing it as “exclusively a decision of the American government” to which Greece has “no connection whatsoever.” Opposition parties pushed back, with PASOK arguing the government had “exposed itself” by tolerating conduct beyond normal diplomatic norms, and ELAS calling for formal explanations. The appointment of Josh Huck — a career diplomat and former deputy assistant secretary for Southern Europe and the Caucasus, with direct experience on Cyprus, Greece, Malta and Turkey — as interim ambassador was read in Athens as a reassuring signal of institutional continuity, even as officials privately acknowledged the risk of losing the high-energy bilateral momentum Guilfoyle had cultivated. The timing was doubly awkward: Guilfoyle’s departure coincided with Rubio’s visit and the $4 billion FMS announcement, risking overshadowing one of the most substantive weeks in bilateral relations in years.
On the Great Sea Interconnector (GSI), Nexans submitted its seabed survey permit application on 8 October to the Greek Foreign Ministry, seeking authorisation for the VB Abeille Marengo to conduct work through end-2026. The Foreign Minister is expected to forward a recommendation to the interministerial marine research committee around 18 October, with a Navy Hydrographic Service Navtex to follow within 48 hours of a favourable decision — putting resumption of surveys weeks away rather than months. Turkey’s Blue Homeland legislation, meanwhile, appears to be sliding again: it has not appeared on the Turkish parliament’s autumn agenda, with Ankara reportedly watching how Athens proceeds on the GSI and managing the timing around October as a critical month. Athens is reading the pause as tactical rather than strategic, and is pressing ahead with the survey authorisation regardless.
Politically, the social media under-15 ban — scheduled for a full parliamentary vote on 22 October with implementation from 1 January 2027 — is being deployed as a deliberate non-economic mobilisation tool. With 80% public approval and direct relevance to the 45-54 parent demographic, where ND support has fallen nearly 19 points since 2023, the measure is one of the few issues capable of cutting across cost-of-living fatigue. Implementation risks remain — age verification complexity being the primary one — but the political calculation is clear.
PM Mitsotakis, in an interview this week, set 25% as the electoral threshold at which his leadership would face serious questions, framing his goal as an outright majority and defending his party’s ideological positioning. On the centre-left, pressure is building from within PASOK and ELAS for a progressive alliance, though the personal hostility between Tsipras and Androulakis makes any formal arrangement a distant prospect. Tsipras this week attempted to lower the bilateral temperature, saying his opponent is “Mitsotakis, not Androulakis” — a gesture aimed at positioning ELAS as the natural pole of a future anti-incumbent coalition rather than a fratricidal competitor.
The fiscal data continued to outperform: a €162 million budget surplus for January-September against a projected €1.89 billion deficit, with a primary surplus of €7.58 billion against a €5.12 billion target. Net revenues exceeded targets by €2.52 billion. The IMF, however, revised Greek inflation upward to 4.2% for 2026 and 3.6% for 2027 — both significantly above government and Bank of Greece forecasts — while maintaining the 1.8% growth projection. The public debt trajectory remains on course, with the IMF projecting 136% of GDP in 2026 and 111.1% by 2031 — at which point Greece’s debt would sit below France’s and Belgium’s.
The European Commission granted Greece an exclusive energy resilience escape clause covering up to 0.3% of GDP annually and 0.6% cumulatively through 2028, giving Athens additional fiscal room to fund energy infrastructure without breaching the expenditure growth ceiling. Greece also confirmed access to a combined €100 billion-plus in post-RRF national and European investment financing through 2034, though officials cautioned the figure combines existing commitments, future allocations and anticipated MFF resources rather than new money.
The structural data this week added nuance to both the opportunity and the challenge. Athens ranks third most expensive in Europe for home purchases relative to income, requiring sixteen years of average salary to buy a 70-square-metre new-build — a housing affordability figure that compounds the demographic and household stress data seen in recent weeks. Greek consumer spending on grocery products is stable at around €26 billion annually, but dietary patterns are shifting significantly: olive oil purchases down 35% since 2008, beef down 29%, processed meats down 35%, with ready meal consumption rising from 0.24 kg per capita in 2015 to 3.34 kg in 2025 — a signal of both financial pressure and lifestyle change.
On the positive side, the Acropolis recorded a post-pandemic record of 4.6 million visitors in 2025, up 32% on 2019, now requiring a 20,000-person daily cap. Greek universities are attracting growing international student numbers — around 3,200 across undergraduate and postgraduate programmes — with medicine accounting for the largest share and ten new undergraduate programmes in preparation for 2027-28. The US-Greece economic relationship, detailed in a new Embassy of Greece Washington report, encompasses €13-14 billion in annual bilateral trade, €3.1 billion in cumulative US investment since 2015, and a fast-deepening footprint across energy, technology, pharmaceuticals, hotels and shipping.
Taken together, this is a Greece that continues to perform well by institutional and macroeconomic measures, while confronting a widening gap between those headline indicators and the lived experience of households — a gap the Guilfoyle affair, the IMF’s inflation revision and the housing affordability data all illuminate in different ways, and one that the government’s pre-electoral strategy is now explicitly designed to address.